CoreWeave Wants $3 Billion More Debt — Its Power Pipeline Is Now 4.2 Gigawatts
The Nvidia-backed cloud provider paired convertible debt with a potential 35-million-share programme, showing that AI compute demand and financing dilution are growing together.
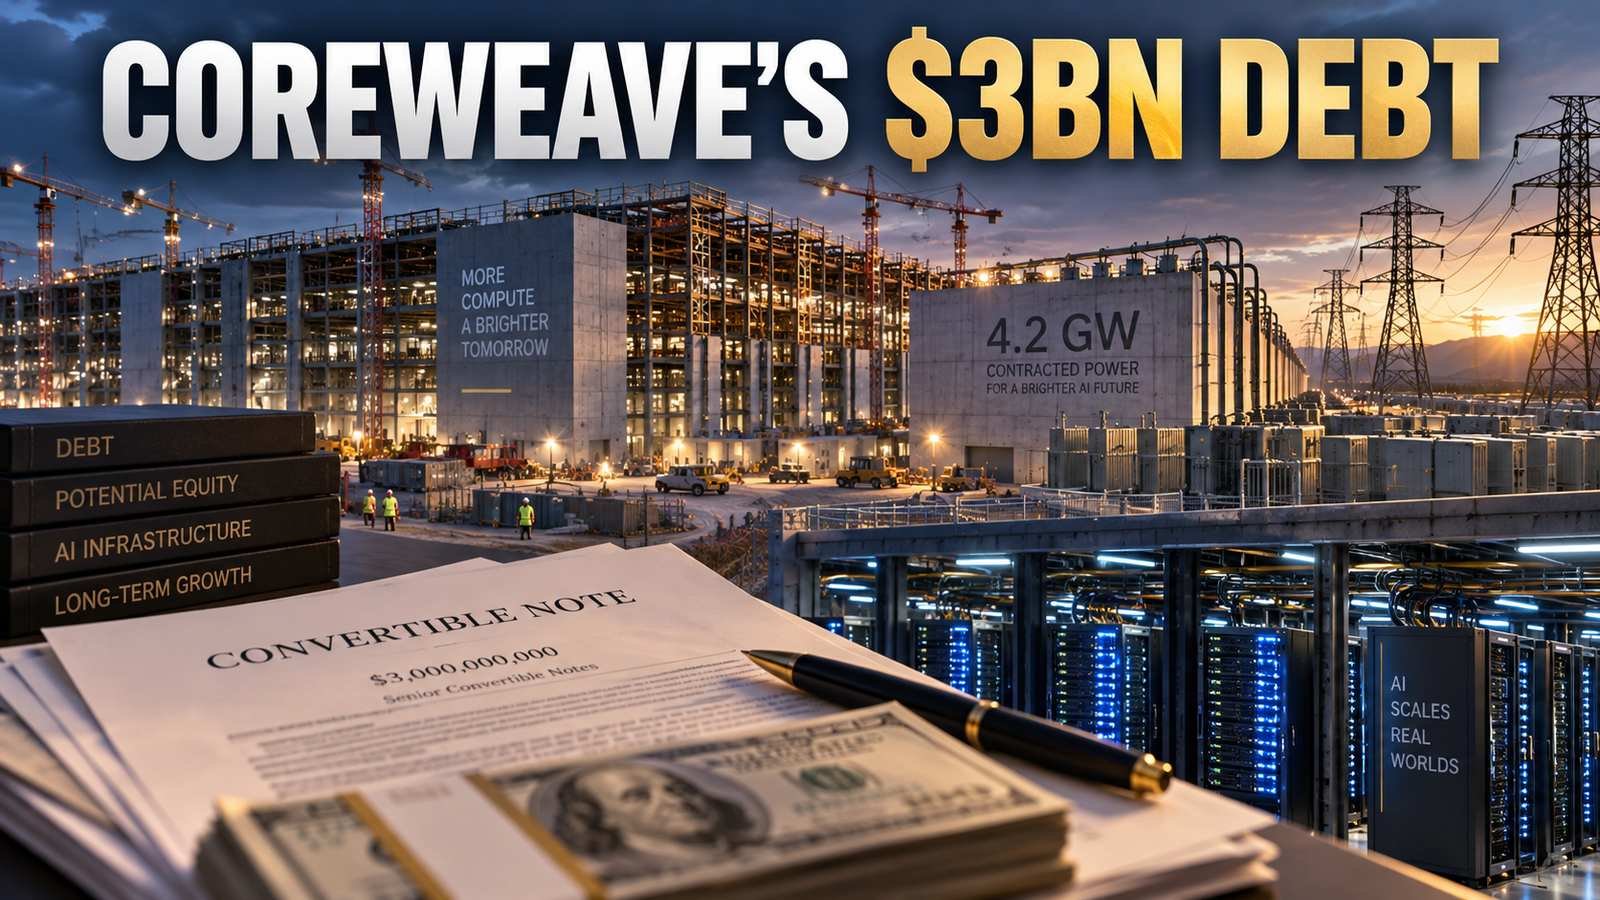
CoreWeave Wants $3 Billion More Debt — Its Power Pipeline Is Now 4.2 Gigawatts
*By PriceVia Markets Desk | Published September 18, 2026 | Updated September 18, 2026*
Why this matters now
The Nvidia-backed cloud provider paired convertible debt with a potential 35-million-share programme, showing that AI compute demand and financing dilution are growing together.
Key points
- CoreWeave launched a $3 billion convertible offering with a $500 million buyer option. - A separate at-the-market programme can sell up to 35 million shares, worth about $2.92 billion at the referenced price. - Contracted power increased to 4.2 GW and backlog was $104.2 billion, but infrastructure must be financed before revenue arrives.
The numbers
| Metric | Value | Context | |---|---:|---| | Convertible debt | $3bn | Base offering | | Buyer option | $500m | Additional debt | | ATM shares | Up to 35m | Potential equity | | Implied ATM value | $2.92bn | At referenced close | | Contracted power | 4.2 GW | Up from 3.7 GW | | Revenue backlog | $104.2bn | Q2 disclosure |
What happened — confirmed facts
CoreWeave said it will use part of the convertible proceeds for dilution protection and the balance for operations. Shares fell more than 3% early, reflecting concern about financing and potential equity issuance despite strong AI demand. [S1, S2] The company reported compute contracts priced near $40 million per megawatt annualised, 4.2 GW of contracted power and more than $25 billion of additional commitments after its $104.2 billion backlog disclosure. [S1, S3]
What everyone is watching
Backlog quality is central: contract duration, customer concentration, cancellation rights and the schedule for available power determine how much becomes cash. Convertible debt lowers current cash interest relative to straight debt but creates potential dilution. The capped-call or hedge structure can reduce dilution only within defined share-price ranges.
What the market may be missing — PriceVia analysis
PriceVia analysis: power commitments are both asset and obligation. Securing 4.2 GW supports growth, but data centres, chips and grid connections require capital long before utilisation becomes certain. The financing stack is part of the product economics. If capital becomes more expensive, the price charged for compute must rise or returns fall even when servers remain fully booked.
Positive case
Backlog converts on schedule, utilisation stays high and long-term contracts support an investment-grade credit path. Financing funds profitable capacity before dilution becomes material.
Downside case
Projects delay, customer concentration bites or rates stay high. Debt and equity issuance expand faster than free cash flow, weakening per-share value.
What would change the story
Final pricing, hedge terms, SEC filings, power energisation and backlog conversion will determine the true cost and quality of growth.
Related stocks and themes
CoreWeave, Nvidia, AI cloud providers, data-centre developers, utilities, convertible bonds and hyperscaler capital spending.
How to read it
Model debt, dilution and project timing together; do not value backlog as cash or contracted power as already operational.
Reader checklist
- Confirm final debt terms in a primary disclosure before changing the thesis. - Compare atm issuance with the headline narrative; they may move in different directions. - Reassess after new information on power energisation rather than treating the first report as a completed outcome.
PriceVia View
AI demand is real, but so is the bill. CoreWeave’s next test is turning gigawatts and backlog into returns faster than financing claims accumulate.
Sources and timestamps
- [S1 — Reuters: CoreWeave launches debt sale](https://www.reuters.com/legal/transactional/coreweave-launches-3-billion-convertible-debt-sale-2026-09-17/) — published 2026-09-17 13:30 UTC; accessed 2026-09-18T13:15:00+05:30 - [S2 — CoreWeave investor relations](https://investors.coreweave.com/) — published 2026-09-18; accessed 2026-09-18T13:15:00+05:30 - [S3 — SEC EDGAR CoreWeave filings](https://www.sec.gov/edgar/browse/?CIK=1769628) — published 2026-09-18; accessed 2026-09-18T13:15:00+05:30 - [S4 — CoreWeave company news](https://www.coreweave.com/blog) — published 2026-09-18; accessed 2026-09-18T13:15:00+05:30
Visual disclosure
Hero visual created specifically for this article. Thumbnail text: “COREWEAVE'S $3BN DEBT”. It is an editorial illustration, not a market-data, legal or regulatory screenshot.
Market-risk disclaimer
This article is for market education and information only. It is not investment advice, a recommendation or a promise of returns. Market prices, policy decisions, deal terms and forecasts can change. Verify the latest primary disclosures and assess suitability and risk independently.
- Final debt terms
- ATM issuance
- Power energisation
Risk context: This article is for market education and information only. It is not investment advice, a recommendation or a promise of returns. Market prices, policy decisions, deal terms and forecasts can change. Verify the latest primary disclosures and assess suitability and risk independently.
- reuters.com2026-09-17 13:30 UTC
- investors.coreweave.com2026-09-18
- sec.gov2026-09-18
- coreweave.com2026-09-18
Related PriceVia analysis
Delhi Metro Carried a Record 82.45 Lakh Riders in One Day — A Bus Strike Revealed Its Spare Capacity
A sudden DTC bus disruption pushed Delhi Metro to a new daily record, testing whether the network can absorb shocks without letting reliability deteriorate.
India Gave Compressed Biogas an Assured Buyer — Price Support Could Finally Turn Waste Into Bankable Fuel
New GOBARdhan rules address the two questions that have stalled many waste-to-gas projects: who will buy the output and how predictable will the price be.
India's New ESG Assurance Standard Starts in April 2027 — Two Big Carve-Outs Will Shape What Investors Can Trust
SSA 5000 broadens assurance across climate, labour and biodiversity disclosures, but excludes joint audits and forward-looking statements from the international framework.
India's Forex Reserves Fell $4.92 Billion — The $780.78 Billion Buffer Is Being Put to Work
The weekly decline arrived as traders reported central-bank dollar selling near a rupee record low, illustrating that reserves are insurance to be deployed—not a score that must rise every week.