The Fed Says Inflation Is Too High Everywhere — Oil Is No Longer a Sufficient Excuse
Neel Kashkari backed the latest quarter-point rate increase and argued that core pressure remains excessive, keeping another hike alive even if energy shocks fade.
What changed, why it matters, and what most people may be overlooking.
Neel Kashkari backed the latest quarter-point rate increase and argued that core pressure remains excessive, keeping another hike alive even if energy shocks fade.
The Federal Reserve lifted its target range to 3.75%–4.00%, and 16 of 18 policymakers expect at least one more increase; markets now face an inflation fight extending well beyond one meeting.
Seven straight declines erased about 1.5% despite near-daily intervention; the next move depends on whether 96 becomes a new trading range or only a defended psychological level.
The benchmark yield returned to a level last seen in 2023 as oil, inflation, debt supply and Fed expectations collided; the key consequence is a higher hurdle rate for almost every risk asset.
Goldman Sachs joined the tightening camp and markets price an 87% chance of a quarter-point increase as oil above $100 and hotter producer prices revive inflation risk.
August CPI accelerated, real wages fell again and markets priced an 87% chance of a quarter-point hike; the near-5% Treasury yield is tightening conditions before the Fed votes.
US spot Bitcoin funds posted their best daily inflow since January, led by BlackRock’s IBIT, before strong payrolls revived Fed-hike expectations and cooled Friday’s risk appetite.
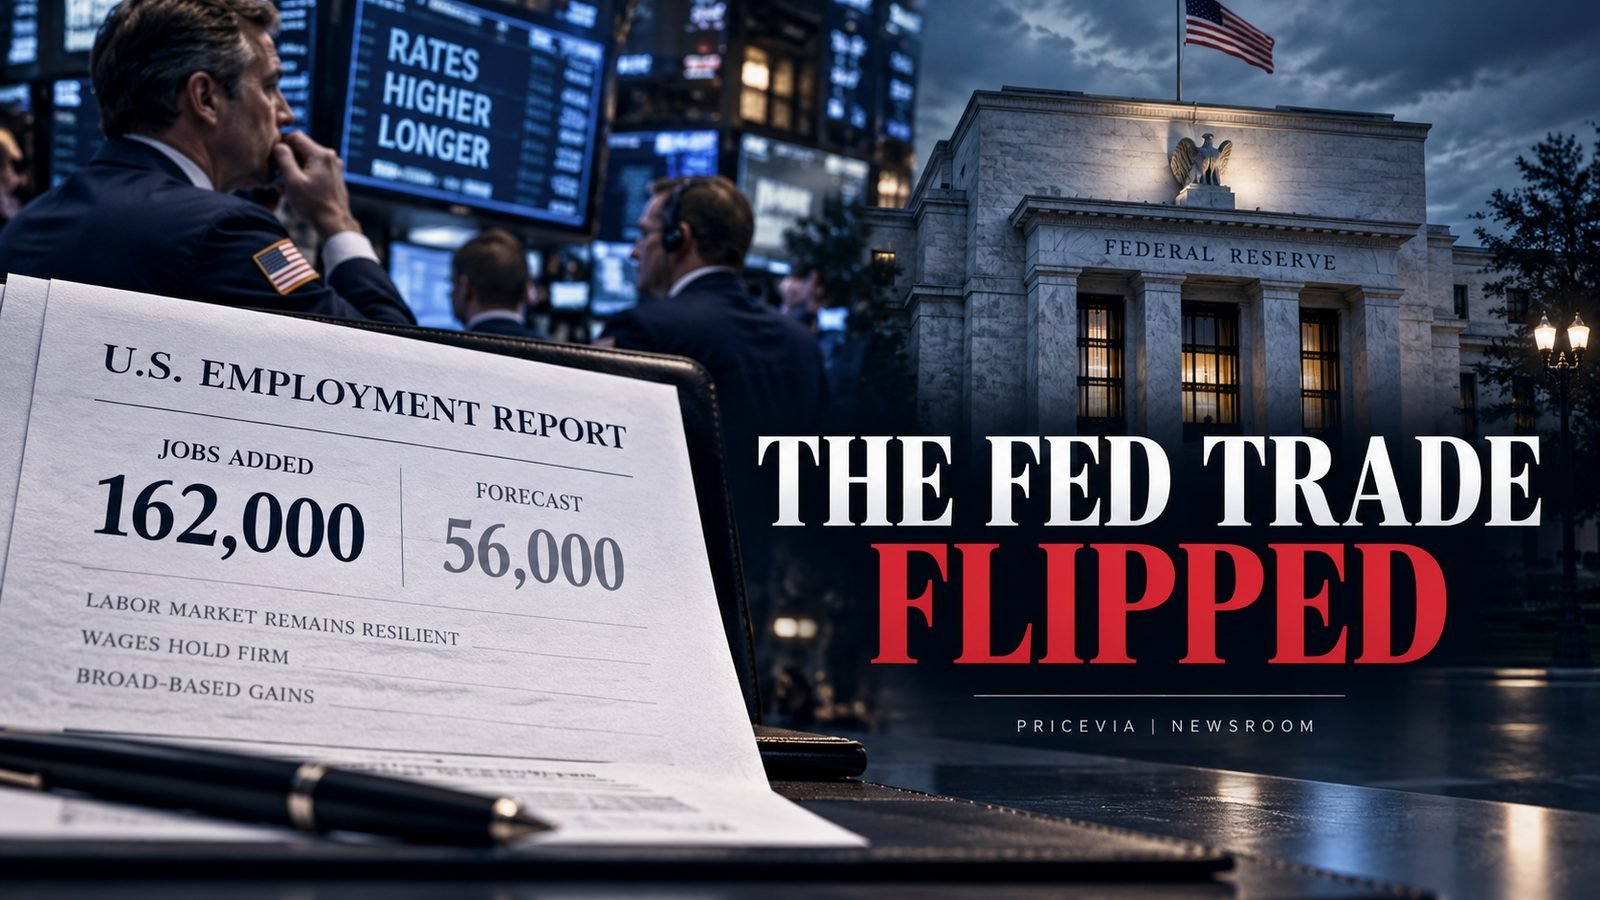
August payrolls nearly tripled the consensus estimate, pushing two-year yields to 4.37% and lifting the implied probability of a September rate increase to roughly 62% before inflation data.